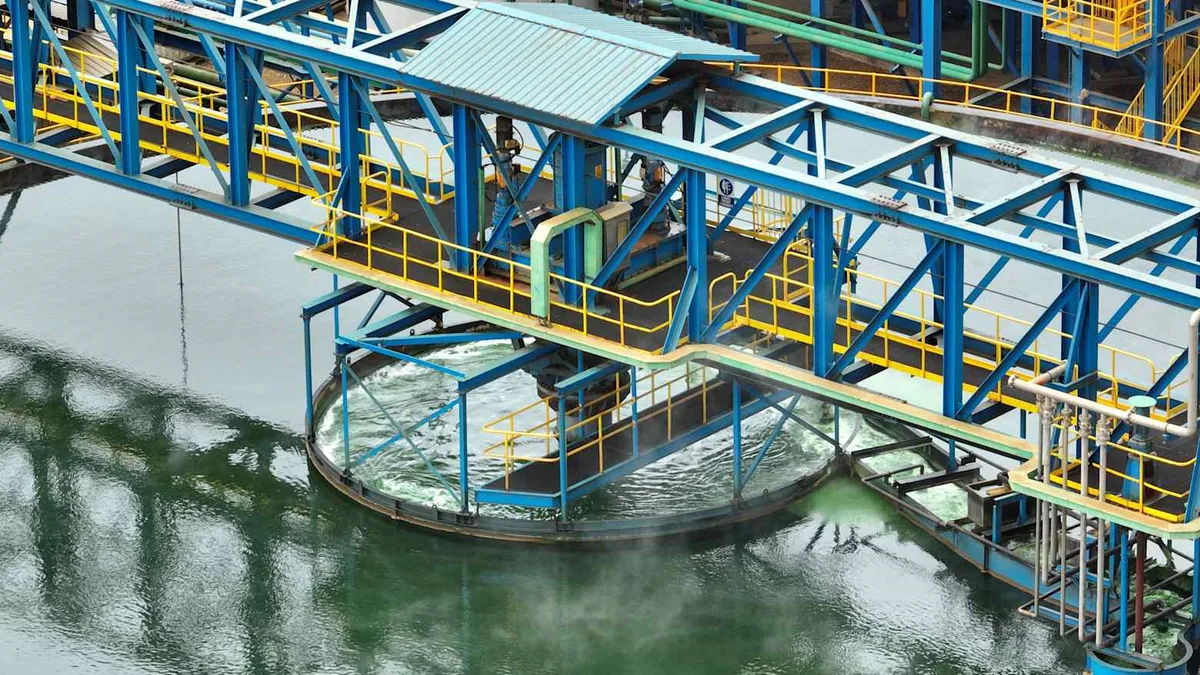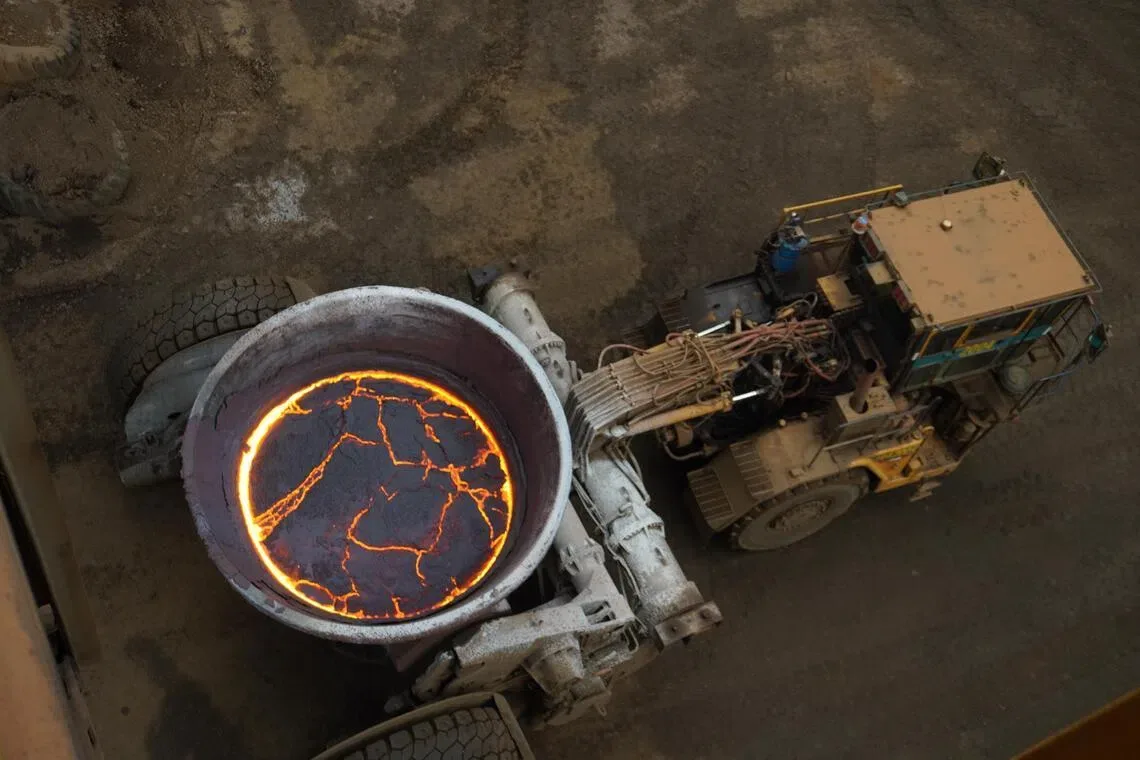
Indonesia, the world’s largest nickel producer, faces growing policy uncertainty that is pushing the global nickel market toward its first supply deficit in five years, market analysts say [1]. The country accounted for more than 60% of global mined nickel output in 2025, a sharp rise from just over 30% in 2020, cementing its central role in the market [2].
Chinese companies including Tsingshan Group and Lygend Resources played a key role in developing Indonesia’s nickel industry, building smelters and industrial parks that supported its rapid production growth [2]. However, since President Prabowo Subianto took office in late 2024, a series of policy shifts have unsettled foreign investors. These include tighter mining quotas, tax hikes, and a higher benchmark price for minerals [2].
Indonesia outlined plans in late May 2026 to bring exports of coal, palm oil, and ferro-alloys under centralized state control, although nickel pig iron was excluded. The move raised further concerns among investors about increased government intervention in commodity markets [2]. Tim Hoff, a senior mining analyst at Canaccord, said, "It’s definitely negative for the industry. If you have the government adding bureaucracy and controlling what you can sell your commodities for, then that will impact the scale of your investment" [2].
Foreign direct investment (FDI) into Indonesia fell by 6% in 2025 after a 19% growth in 2024. Mining investment, which peaked in 2024, has since plateaued, reflecting increased caution among investors [2]. In response, Chinese nickel firms are scouting alternative projects in Africa, with Tsingshan targeting Madagascar and Lygend Resources focusing on Tanzania, while also restarting operations in New Caledonia [2].
The global nickel market is also affected by disruptions in sulfur supplies tied to the Iran war, compounding supply risks from Indonesia's policy-driven uncertainties [1].
In 2020, Indonesia banned nickel ore exports, accelerating domestic smelter development led by Chinese companies and helping boost the country’s nickel output share from about 30% in 2020 to 60% in 2025 [2]. Since President Prabowo’s arrival in late 2024, policy changes have increased state control and mining costs, challenging the investment climate [2].
The next major event is Indonesia’s ongoing implementation of its centralized export controls announced in May 2026, with close attention expected on how this affects nickel producers and foreign investment in the coming months [2].