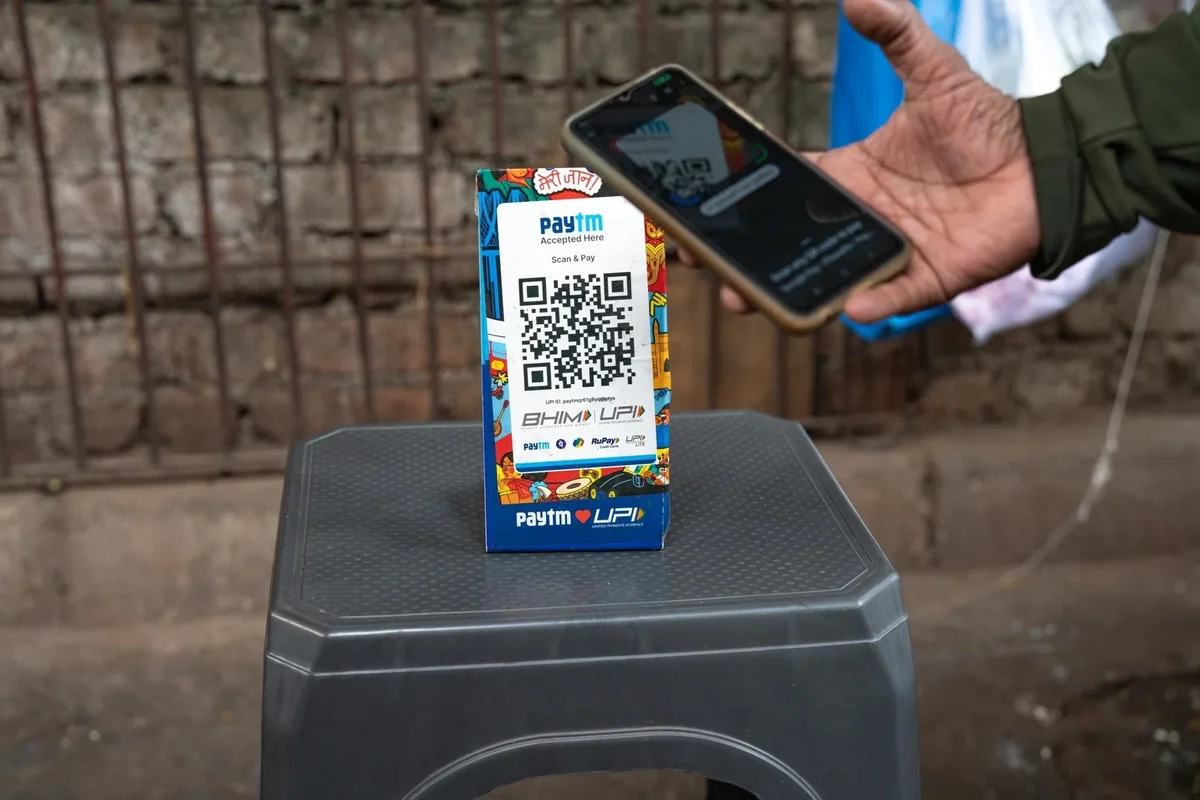
Paytm announced it will hire about 4,000 people over the next nine months to expand its merchant network and AI-driven product offerings, aiming to grow its workforce by around 10 percent from 40,000 employees today [1, 2]. The company is simultaneously laying off roughly 400 staff, about 1 percent of its total headcount, following its current performance appraisal cycle [1, 2].
This personnel reshuffle comes as Paytm continues to recover from regulatory challenges. The Reserve Bank of India canceled the operating license of Paytm Payments Bank in April 2026, forcing a formal wind-down of the bank [1, 2]. Most staff at the Payments Bank were laid off over the past two years, with some absorbed in other parts of Paytm’s fintech group. The remaining few hundred employees will be let go as the bank completes its shutdown [1, 2].
Despite the disruption, Paytm has posted four consecutive profitable quarters and is shifting focus to AI and product innovation. A company statement said, "Over the last two months, we have added more than 800 people and are in the process of recruiting a further 4,000" [1]. Paytm plans to continue hiring, including senior leadership roles across product, technology, and AI teams until March 2027 [1, 2].
Paytm has transformed since its launch in 2016, evolving from a prepaid mobile recharge service into one of India’s major digital payments and banking platforms [1, 2]. However, its shares, which have gained about 7 percent over the past year, still trade more than 50 percent below their 2021 initial public offering price [1, 2].
Since the RBI’s regulatory actions began two years ago, Paytm has cut around 4,500 jobs in total, including the current round of layoffs, as it refocuses its business strategy [1, 2].
The company expects to complete its current hiring cycle by March 2027, expanding its workforce to support new AI-driven offerings and merchant services [1, 2].